 Chloe M.Google review
Order arrived damaged and nobody has replied to my email in three days.

Treat every "money debited, payment failed" message as a complaint with a deadline, and answer it in two steps. Acknowledge at once in private, without asking for anything sensitive in public. Then find out which of the possible states the money is really in, and tell the customer that specifically. Never tell someone the money "will be back shortly" until you have looked. A person handles every case involving money.
The same words from a customer can mean very different things. Your agents need to know which one they are looking at.
| Your records show | What it means | What the customer should hear |
|---|---|---|
| Authorisation only, nothing settled | A hold that should drop off | It's a hold, the money hasn't moved, and the date you will recheck |
| Debit confirmed, merchant or payee never credited | A true failed payment | It will be reversed, the clock that applies, and a reference |
| Debit confirmed, merchant received it, your app showed failure | The payment worked and your status was wrong | It went through, proof it was received, and that they shouldn't pay again |
| Customer paid again after the failure | Possible double payment | One will be returned, and which one |
| A debit the customer never made | Possible fraud | Go straight to your unauthorised transaction process |
| No trace at your end | May be the bank, or another provider | What you checked, and what to ask their bank for |
Do not skip the third row. A customer who sees "failed" often pays again, and then you have two problems.
The principle that holds almost everywhere: if you are a regulated payment firm, a complaint starts a clock when you receive it, wherever it arrives, and you owe a reasoned answer before it runs out. If the customer isn't satisfied, an outside body can usually take it further. What differs is the length of the clock and whether money or compensation is due automatically.
Many app businesses are not the regulated party. A merchant or software company may sit in front of a bank or licensed provider that holds these duties. Find out who owns what before you need it. This is general information and not legal advice. Check the rules in your own market, and your licence terms.
| Market | Rule | Clock |
|---|---|---|
| US | Regulation E on electronic fund transfer errors. An enquiry about whether a debit posted, with no error asserted, does not start it | 10 business days to investigate, or 45 with provisional credit, 90 for point of sale debit. Results in 3 business days, correction in 1 business day |
| UK | FCA rules for payment firms and e-money issuers | Unless resolved within 3 business days, the firm must confirm receipt in writing. Normally answer in 15 business days, 35 at most with an explanation. The customer has 6 months from the final response to go to the ombudsman |
| EU | Your Europe summary of EU payment rules | Written answer in 15 days, 35 in exceptional cases. A new Payment Services Regulation was provisionally agreed in November 2025 and needs formal adoption, so check its status |
| Australia | ASIC RG 271 for licensed firms. ePayments Code for subscribers | Acknowledge within 24 hours or one business day, or as soon as practicable. Answer within 30 calendar days. Then AFCA |
| India | RBI turnaround rules, 2019 | See the table below. Compensation is credited automatically |
| Canada | FCAC guideline for banks | 56 days. A revised guideline issued on 23 June 2026, effective 23 June 2027, says the period will not be paused for any reason. A revised guideline was issued on 23 June 2026, effective 23 June 2027 |
| Singapore | MAS E-Payments User Protection Guidelines, December 2024 | Unauthorised transaction claims: 21 business days, or 45 for complex cases. Separate duties cover non-card payments sent to the wrong recipient |
India's table is unusually specific. From the RBI circular, where T is the calendar date of the transaction:
| Payment type | Failure | Reversal by | If late |
|---|---|---|---|
| UPI transfer | Debited, payee not credited | T+1 | ₹100 a day |
| UPI merchant payment | Debited, merchant not confirmed | T+5 | ₹100 a day |
| IMPS | Debited, payee not credited | T+1 | ₹100 a day |
| Card at point of sale or e-commerce | Debited, merchant not confirmed | T+5 | ₹100 a day |
| ATM | Debited, cash not dispensed | T+5 | ₹100 a day |
RBI calls these outer limits, and compensation must be credited without the customer asking. If there is no redress in that time, the customer can go to the Integrated Ombudsman. RBI consolidated many of its regulatory circulars into Master Directions in November 2025. We could not confirm whether that touched this circular, so check the current text.
Australia has two details worth copying anywhere. Under RG 271, a post on a social channel the firm owns or controls counts as a complaint if the author is identifiable and contactable, and the firm must protect the customer's privacy when it answers. Firms are also expected to spot complaints without being told. The ePayments Code, last updated in June 2022, says a holder is not liable for loss caused by a failure of a system or equipment to complete a transaction it accepted. The Code is voluntary today. Treasury's March 2026 factsheet proposes a rule-making power for a mandatory, revised Code, and said legislation would be finalised for introduction in 2026.
| Situation | Owner | First move | Never |
|---|---|---|---|
| Single debit-and-fail report | Payments agent | Acknowledge, check the ledger | Say "it will be back soon" before checking |
| Same failure from many customers | Payments lead and engineering | Raise an incident, find the route that failed | Answer each as a one-off |
| Payment worked, app showed failed | Payments agent | Show proof, warn against paying again | Refund without confirming |
| Customer paid twice | Payments agent | Return the extra payment | Ask them to wait for the first to resolve itself |
| Unauthorised debit claim | Fraud team | Secure the account, follow fraud process | Treat it as a failed payment |
| Public post | Support, trained on privacy | Short reply, move to private | Ask for account or transaction numbers |
| Customer in hardship or distress | Senior agent | Prioritise, offer a person | Send a template |
Write these in the customer's language when you can. Have a person check anything that mentions money.
First reply, private
Hi Jun, I'm sorry, that's stressful when it's your bill money. I've passed this to our payments team and I'm checking what happened to the $240. To find it I need the date and the last 4 digits of the payment reference in your app. Please don't send your full card number or PIN, we'll never ask for those. You'll hear from me by 6pm.
Public reply
Sorry about this, Layla. Please don't share account details here. We've messaged you privately and our payments team is on it.
Update when there is no news
Hi Jun, no result yet. The bank has not confirmed whether the $240 was credited or returned, and I don't want to guess. I've asked again and will write to you by noon tomorrow, even if nothing has changed.
Closing reply, money returned
Hi Jun, the payment failed at the bank's end and the $240 was returned on 7 November. Your reference is 58120. It should show in your account now, or within a day or two depending on your bank. If it isn't there by 11 November, reply and I'll chase it with that reference.
Hard case: the payment actually went through
Hi Jun, I've checked this and I'm sorry for the confusion. Our app showed "failed", but the electricity company received your $240 on 6 November, reference 58120. Please don't pay again. The error was on our side, and we've fixed the status in your app. If they say they haven't got it, send me their message and I'll deal with them directly.
Hard case: you can't give the money today
Hi Layla, I know you need this today and I wish I could send it now. The reversal has to come back through your bank, and it has until 12 November. I can't speed that up, but I'm tracking it and I'll tell you the moment it lands. If it hasn't by then, I'll escalate it and tell you what happens next.
Formal answer, when the clock requires one
Dear Layla, this is our final response to your complaint of 3 November. We found [what happened]. We have [what we did]. If you are not satisfied, you can contact [the ombudsman or external scheme for your market], at [contact details].
Check what your regulator requires in that letter. RG 271, for one, sets minimum content for the response.
Times are a suggested starting point. They are not a benchmark, and any regulatory deadline in your market overrides them.
It is working when customers get a specific answer about their own money on the first proper reply, and no case gets close to its deadline unnoticed.
This is an example scenario. The app, people and messages are made up to show how Relay works. It is not a customer story.
Pocketpay is a payments app. One evening a payment route starts failing.
Jun writes on WhatsApp in Mandarin: "我的账户被扣了240美元,但是应用显示付款失败。" ($240 was taken from my account but the app shows the payment as failed.) Layla posts on X in Arabic: "تم خصم المبلغ من حسابي لكن الدفع فشل. @pocketpay" (The amount was taken from my account but the payment failed.) A Google review says: "Paid my bill, money gone, app says failed. Third time this month."
Each message is tagged as a failed payment with money debited and marked for a person. Each customer gets an agent-approved acknowledgement that moves them to a private channel, with no request for card or account numbers in public. Each case goes to the payments team with a summary, so nobody has to repeat themselves.
Reports climb, all naming the same failure, and the theme crosses its normal level. An alert reaches the people named for it, and engineering finds the failing route. Every money case has a response deadline. If one is missed, the escalation ladder moves it up until someone owns it. The payments agent checks each transaction in Pocketpay's own system and sends the customer the specific result.
Tagging, theme grouping, crisis alerts, routing to the payments team, SLA clocks, the escalation ladder and drafted replies that a person approves run in Relay today. Sending on WhatsApp, X, Google reviews and email needs each channel's token. Every money case goes to a person. Relay does not move money.
Payment and transaction lookups are on the way. Refunds and reversals stay with a person. Today the payments agent checks the transaction in your own system and uses Relay to reply and track the case. SLA clocks are ones you set, so enter your regulatory dates yourself. If failed payment complaints are your hardest queue, contact us. For a merchant's double charge, see the charged twice guide. For when one failure hits many customers, see handling a ticket spike.
Under most of the rules above it runs from when the firm receives the complaint. ASIC counts from the day after receipt, for example, and Canada's revised guideline, effective 23 June 2027, starts it the day the complaint is first communicated, by any channel. Check how your regulator counts.
It depends on the market. In Australia, RG 271 treats a post on a firm's own channel as a complaint if the author is identifiable and contactable. Even where it isn't required, handle it the same way, because it is the same customer with the same problem.
Say what your records and the rules show for that payment type, and give a date you will check. India's RBI timelines are specific, but other markets depend on the bank and the rail. Don't quote a blanket number.
Possibly not directly, but they probably apply to someone in your payment chain, and your contract with them may pass duties to you. Find out which entity holds the licence and who must answer complaints. Take advice if you are unsure.
No. Relay sends every money case to a person. Refund actions within limits a business sets are on the way, and even then a person decides anything outside those limits.
Never in public. When a detail is needed, the draft asks for it in a direct message or other private channel. A person approves each draft before it goes out.
 GuidesIntroducing Relay: your online reputation in one placeWhat Relay is, the gap it was built for, what it does today, what it does not do yet, and who should choose something else.29 October 2026 · 6 min read
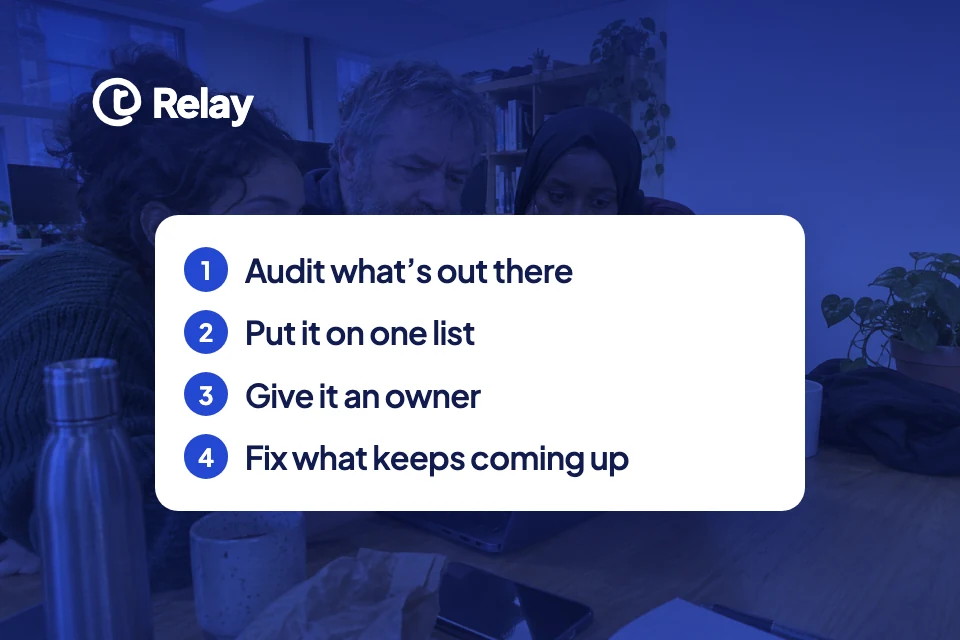 GuidesHow to do online reputation management, step by stepFind what people say about your business, answer it within the rules, fix what caused it. A plan, a triage table and replies you can copy.9 November 2026 · 11 min read
 GuidesHow to automate customer support without trapping your customersWhat to automate, what to keep with a person, what the law says about AI disclosure, and how to tell whether automation is really working.9 November 2026 · 12 min read
Get a personalised 30 minute demo on your own channels and policies. We show you Relay handling your real conversations, then set it up with you.
Brands we work with